The complete personal finance app for financial resilience
Average net worth by age
Across U.S. households, median net worth is $192,900 and mean net worth is $1,063,700 (Federal Reserve, Survey of Consumer Finances, 2022). By age, the median runs from $39,000 under 35 to $409,900 at 65 to 74. Enter your household's assets, debts and spending to see your net worth and how long it would carry you.
WealthAge is a personal finance app, on the same shelf as Copilot Money and Monarch Money. Your accounts, transactions, spending, cash flow and net worth live in one place. It also reads how prepared that money leaves you, and shows where every number came from.
Your results from WealthAge’s personal finance app calculator
Enter your own figures and it becomes yours.
Example net worth
$125,000
Total assets minus total debts.
Example runway
24.7 months
How long your liquid assets would cover your monthly essential spending, at the 40% liquid share set above. Debt payments count only through the monthly figure you entered; balances you owe are not netted out.
Your debts exceed your assets, so this figure describes cash on hand rather than what you own.
Add your monthly spending above to see this number.
Waiting on a valid number above.
Example percentile
Higher than about 48% of households your age (40–44).
Federal Reserve SCF 2022.
Ranked against households, the unit the Federal Reserve measures. If you entered one person’s accounts rather than a household’s, this rank reads high.
This rank comes from Federal Reserve data for your age band. It describes a group of households, not you.
This is an estimate from the numbers you entered. It can’t see your retirement account vesting schedules, other income sources, insurance coverage, or how quickly your specific assets could actually convert to cash.
This is a useful estimate. Your complete financial picture may change it.
WealthAge can calculate this using your actual accounts, obligations, cash flow and resilience, and keep it updated as your life changes.
Connect or upload, and see your net worth from your real accounts, kept current, with your resilience read against the same cash-flow picture.
See how it worksMedian net worth by age climbs unevenly, and the mean climbs faster
A single average is a poor stand-in at any age: the gap between what's typical and what's average widens the older a household gets. The Federal Reserve’s Survey of Consumer Finances groups households into six age bands by the age of the household’s reference person, reported in 2022 dollars; the 2026 columns apply a WealthAge CPI-U adjustment detailed in the chart caption below. The full method and its limits are further down this page.
Median net worth by age (filled bar), with the mean printed beside each row, 2022 dollars, Federal Reserve SCF 2022. All households shown in brass as the population reference.
| Age of household head | Median, 2022 $ | Median, June 2026 $ (adjusted) | Mean, 2022 $ | Mean, June 2026 $ (adjusted) |
|---|---|---|---|---|
| Under 35 | $39,000 | $44,500 | $183,500 | $209,390 |
| 35–44 | $135,600 | $154,730 | $549,600 | $627,150 |
| 45–54 | $247,200 | $282,080 | $975,800 | $1,113,490 |
| 55–64 | $364,500 | $415,930 | $1,566,900 | $1,787,990 |
| 65–74 | $409,900 | $467,740 | $1,794,600 | $2,047,820 |
| 75 or older | $335,600 | $382,950 | $1,624,100 | $1,853,260 |
| All households | $192,900 | $220,120 | $1,063,700 | $1,213,790 |
Source: Board of Governors of the Federal Reserve System, Survey of Consumer Finances, 2022 survey (fielded 2022, published October 2023), Table 2, “Family median and mean net worth, selected characteristics of families, 2019 and 2022 surveys” (the age-of-reference-person rows within it), read and verified directly by WealthAge against the Federal Reserve’s published bulletin on 6 August 2026. The Federal Reserve also publishes these figures on a second, public-data basis that differs slightly from this bulletin; see why net worth figures disagree even when everyone cites the Federal Reserve, below. June 2026-dollar columns calculated by WealthAge from BLS CPI-U series data, retrieved August 2026, and rounded to the nearest ten dollars.
There is no runway column in this table. Runway needs two figures side by side: the money a household can reach, and the bills it has to cover each month. The Federal Reserve does not publish those together, so a months number next to these medians would be one we made up. Your own runway is what the calculator above works out.
By decade
What is the average net worth at 30, 40, 50 or 60?
What is the average net worth in your 20s?
Your 20s don’t get a row of their own. The Federal Reserve’s youngest published bracket is "under 35," which covers your 20s together with the first few years of your 30s, so one figure has to stand in for both. Within that band, median net worth is $39,000 and mean net worth is $183,500 in 2022 dollars ($44,500 and $209,390 in June 2026 dollars, WealthAge CPI-U adjustment). dqydj’s finer 14-band reanalysis of the same underlying microdata, credited above, is the place to look for a narrower slice.
What is the average net worth at 30?
Thirty is the age the brackets change under you. At 30 you’re still inside the Federal Reserve’s "under 35" bracket: median net worth is $39,000 and mean net worth is $183,500 in 2022 dollars ($44,500 and $209,390 in June 2026 dollars). Your 30s as a whole straddle two brackets, the tail end of "under 35" and the start of "35-44" ($135,600 median, $549,600 mean, both 2022 dollars). That jump, roughly 3.5 times on the median, lines up with peak years for career advancement, dual-income households forming, and, for homeowners, equity starting to outweigh a mortgage’s early interest-heavy payments.
What is the average net worth at 40?
At 40 the average stops describing anyone you know. You’re in the Federal Reserve’s "35-44" bracket, where median net worth is $135,600 and mean net worth is $549,600 in 2022 dollars ($154,730 and $627,150 in June 2026 dollars). The mean runs about 4.1 times the median here: a small share of households in the bracket already hold outsized equity or retirement balances, and they pull the average well above what most households in it actually hold.
What is the average net worth at 50?
The 45-54 bracket is the most evenly spread in this table, with the smallest mean-to-median ratio in it, 3.9 times. At 50 you’re inside that bracket: median net worth is $247,200 and mean net worth is $975,800 in 2022 dollars ($282,080 and $1,113,490 in June 2026 dollars). A narrower ratio doesn’t mean less inequality.
What is the average net worth at 60?
Sixty is the last stretch where everything is still pointing the same way: home equity, retirement accounts and a shrinking mortgage balance all working in one direction, before withdrawals begin. At 60 you’re within the "55-64" bracket: median net worth of $364,500 and mean net worth of $1,566,900 in 2022 dollars ($415,930 and $1,787,990 in June 2026 dollars).
What is the average net worth in your 70s?
Your 70s are where the table turns over. "65-74" shows the highest median in it, $409,900, alongside a mean of $1,794,600 (2022 dollars; $467,740 and $2,047,820 in June 2026 dollars). Then "75 or older" steps both figures back down, to a $335,600 median and a $1,624,100 mean, a pattern commonly attributed to retirement drawdowns and, at the household level, the death of a spouse reducing a two-person household’s balance to an individual’s.
Why is this 2022 data?
The Federal Reserve fields its Survey of Consumer Finances every three years: 2019, then 2022, with the next wave, SCF 2025, expected to publish in late 2026 (see the standing re-issue commitment in the limits section below). Newer-looking numbers exist, but none replace it. Bank and fintech posts about "average net worth" are usually model-derived estimates from their own account holders, not a representative national sample. App-dashboard aggregates cover only the people who use that app, a self-selected group already engaged with their finances. Perception surveys, like Charles Schwab’s Modern Wealth Survey, ask what people think "wealthy" means, not what households actually hold. The SCF remains the only source that interviews a representative cross-section of U.S. households about their real assets and debts, every three years. Checked 14 August 2026: no newer wave has published.
Household vs. individual
Two different measurements circulate under the same headline, and most pages that use them do not say so.
Which number should you compare against?
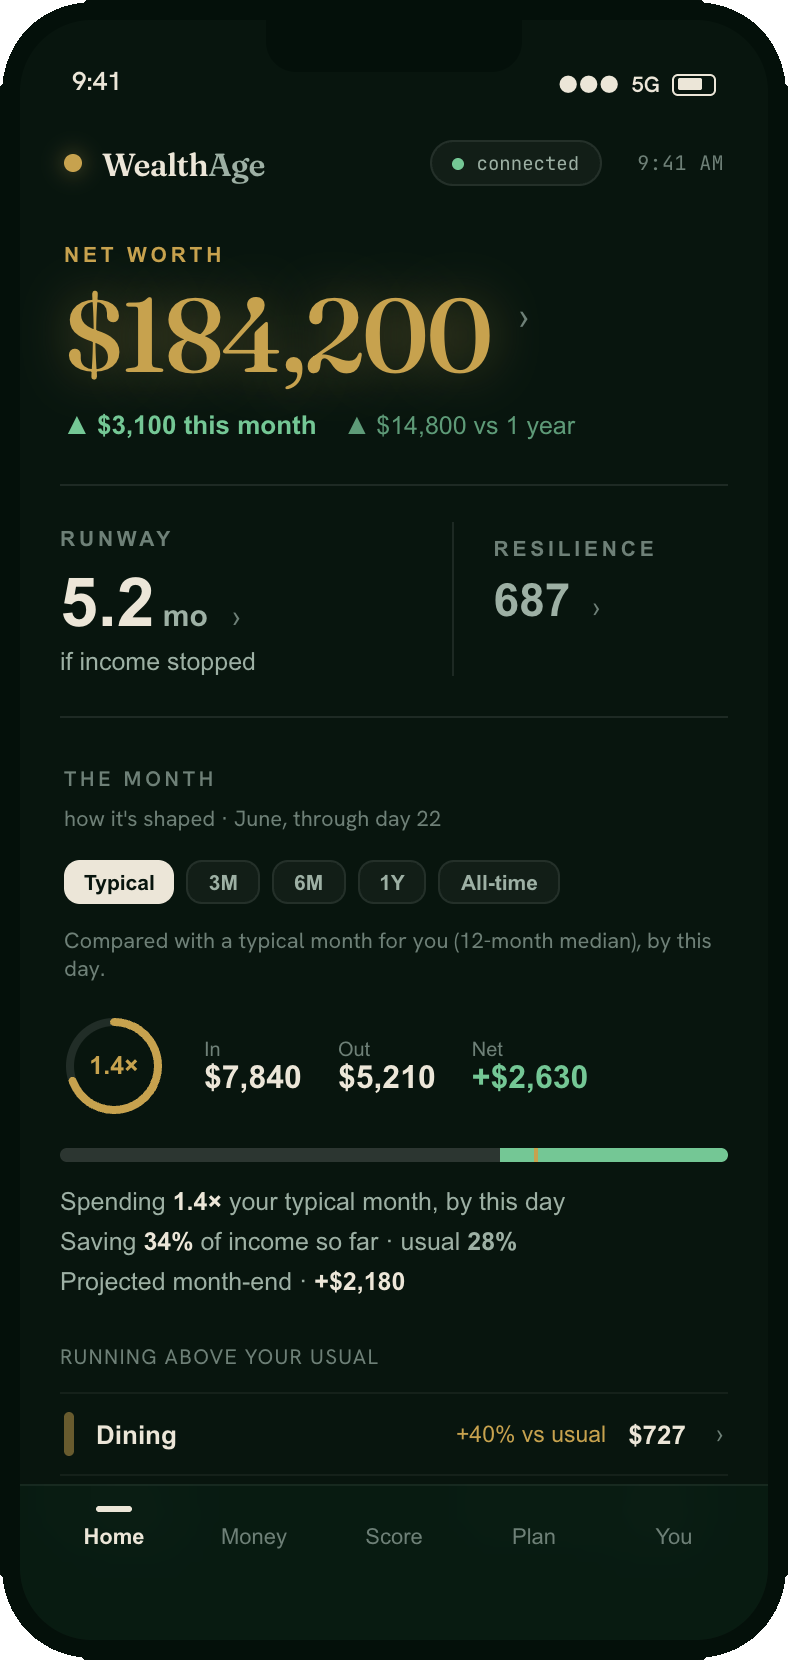
The Federal Reserve’s $192,900 median describes a household: the people who share a home and, often, a mortgage, a car payment and a retirement account. Dashboard apps report something different: the account balances of one individual user, aggregated by age.
Both are real, but they are not the same measurement, and pages in this category confuse them often. Two of the twelve pages WealthAge read on 6 August 2026, Northwestern Mutual and Motley Fool Research, call an SCF median “the average” in prose. None of the twelve reconciles the household figure with an individual dashboard figure.
A dashboard shows one person’s connected accounts. The Federal Reserve counts a whole household’s balance sheet. Set one against the other and you are comparing two different populations, often across two different age slices.
There is a second gap inside each source: the distance between its mean and its median. Nationally, the Federal Reserve’s mean net worth ($1,063,700) is about 5.5 times its median ($192,900), because a relatively small number of very high-net-worth households pull the average far above what a typical household holds. A page that reports only the mean is describing the top of the distribution rather than the middle, whether or not it says so.
The two figures are not interchangeable. Before you take any published number as a benchmark, check whether it describes a household or one person’s connected accounts, and whether it is a mean or a median. Those two checks change what the number means more than the number itself does.
See this reconciled from your own accounts, not a published table.
The other twelve pages
Other pages on this question get some of it right
Of the twelve pages we reviewed on 6 August 2026, NerdWallet is the only one that explains why its figures are from 2022, and it answers the question in its first line: both are habits worth copying. dqydj states a shelf life for its data but never a date it was published, the weaker version of the same habit.
Motley Fool Research is the only page in the bank and publisher set with percentile-group tables, including the bottom quarter’s negative average net worth, checked 6 August 2026. That work is why the distribution table further down this page exists at all. Wealthtender’s percentile tables are deeper still, thirteen age brackets against seven breakpoints, and dqydj re-derives its own from the microdata into a finer bracket set than the Fed publishes itself (more on how dqydj’s granularity compares to this page’s own below). Only one of the twelve, ChooseFI, questions whether rank is the right measure at all, and it still hands the reader a percentile table to place themselves in; none connects the answer to how long the money would last.
Copilot Money, Monarch Money and Empower are the apps people actually run their finances in. They answer this from your own connected accounts instead of from a table. WealthAge answers it the same way, and publishes where every number here came from.
Competitor pages reviewed and verified by WealthAge on 6 August 2026.
Why do net worth figures disagree even when everyone cites the Federal Reserve?
The Federal Reserve publishes family net worth on two different bases. The printed bulletin is computed from its internal, non-public dataset. A separate historic table is computed from the public microdata file anyone can download, the same file this page’s rank feature reads. The two are close but not identical, because the internal dataset is not altered for disclosure the way the public file is. This page’s six-band table above quotes the bulletin; a page that instead reproduces Federal Reserve figures from the public file, as several publishers do, lands on the public-data basis, not the bulletin, which is why two numbers that both cite “the Federal Reserve” can differ.
| Cell | Fed historic table, public data | Fed bulletin, internal data | Difference |
|---|---|---|---|
| Mean net worth, 65–74, 2022 dollars | $1,780,710 | $1,794,600 | −$13,900 (−0.8%) |
Source: Federal Reserve historic tables based on public data, Table 4 (family net worth), and the printed bulletin “Changes in U.S. Family Finances from 2019 to 2022,” Table 2, both Federal Reserve publications. WealthAge’s own pipeline reproduces the public-data figure exactly against the Fed’s own table, verified 9 August 2026 (see the methodology below). This page’s six-band table above uses the bulletin; the rank feature and the twelve-bracket table further down use the public file.
The twelve pages we reviewed, 6 August 2026
- NerdWallet, “Average and Median Net Worth by Age: How Do You Compare?”
- Fidelity, “What's the average net worth for your age?”
- Chase, “Average net worth by age: How do you compare?”
- Empower, “The average net worth by age in America”
- Northwestern Mutual, “Average Net Worth by Age (and How to Keep Yours Growing)”
- Kiplinger, “Average Net Worth by Age: How Do You Measure Up?”
- Motley Fool Research, “Average and Median Net Worth by Age”
- dqydj, “Net Worth by Age Calculator for the United States”
- Of Dollars And Data, “Net Worth by Age Calculator [With Percentiles]”
- ChooseFI, “Net Worth Percentile by Age – Where You Stand and Why It Doesn’t Matter for FI”
- Wealthtender, “Net Worth by Age: How Do You Compare to Your Peer Group?”
- richify.ai, “Net Worth Percentile by Age (US 2026)”
Nine link to the exact page we read, re-checked that day. Empower, Kiplinger and richify.ai are named by their published titles instead: their addresses did not re-verify from our checker on 6 August 2026, and we would rather name a page than link somewhere we have not confirmed.
The complete answer
A number for your age looks like a target, and most pages that hand you one hide the error around it.
This rank states its own error, then asks what a rank can’t answer
Set your age and the calculator ranks you against twelve WealthAge age bands, cut from the Federal Reserve’s public 2022 SCF microdata and verified cell for cell against the Fed’s own published public-data table, all seven medians exact (see the methodology below). The rank states its own error: the Federal Reserve samples the top of the distribution thinly, so accuracy falls off quickly above the 90th percentile, and above the 99th this page says “top 1%” instead of a false point estimate, on the result itself. Of the twelve pages we reviewed on 6 August 2026, dqydj was the only one that stated any top-tail error at all.
A rank still hides what a mean or a median already hides. The mean is pulled up by a small number of very large balances, so most households sit below average at every age, by design of the math. A 35-year-old doctor three years out of residency and a 35-year-old teacher can land in the same percentile band and be nowhere near the same situation.
Even a perfectly accurate percentile answers a static question: where your balance sits today, compared to everyone else’s, at one moment. It says nothing about whether that balance would survive a job loss, a medical bill and a broken transmission at once, which is closer to what net worth actually has to withstand.
This rank compares your net worth against public Federal Reserve data, not against other WealthAge users. The WealthAge Resilience Score is a separate thing: it still does not rank you against a peer group anywhere in the product, and it will not until a comparison model exists for the whole score, not just net worth, that we can publish, test and defend.
The twelve age bands
The six-band table above is the Federal Reserve’s own age grouping. This is the same underlying microdata split finer, dqydj-style, into the twelve bands the calculator’s rank feature uses.
How does your net worth compare within your own age band?
Each column is a percentile of net worth within that age band alone: the 50th column is the median for that band, the same figure the six-band table above reports at coarser age groups. Set your own age and money figures in the calculator above for your own rank instead of reading a column by eye.
| Age band | 10th | 25th | 50th (median) | 75th | 90th* |
|---|---|---|---|---|---|
| 18–24 | −$13,300 | $100 | $10,100 | $32,900 | $190,800 |
| 25–29 | −$10,500 | $3,800 | $30,200 | $129,100 | $291,700 |
| 30–34 | −$15,900 | $11,100 | $89,800 | $185,400 | $537,800 |
| 35–39 | $200 | $17,000 | $141,200 | $387,700 | $870,600 |
| 40–44 | $100 | $23,500 | $134,700 | $436,400 | $1,189,500 |
| 45–49 | $4,700 | $46,500 | $212,800 | $682,700 | $1,428,900 |
| 50–54 | $3,600 | $55,200 | $272,800 | $925,000 | $2,530,100 |
| 55–59 | $3,700 | $85,200 | $320,700 | $1,125,500 | $2,653,700 |
| 60–64 | $8,500 | $79,700 | $394,000 | $1,122,200 | $3,021,000 |
| 65–69 | $2,000 | $69,500 | $394,300 | $1,155,000 | $2,898,500 |
| 70–74 | $9,200 | $123,600 | $433,100 | $1,209,100 | $2,997,400 |
| 75 or older | $10,000 | $93,600 | $334,700 | $975,200 | $2,699,000 |
Percentile values are rounded to the nearest $100, matching the six-band table above; a ~4,600-household survey cannot support finer resolution. *Above the 90th percentile, Federal Reserve sampling error grows quickly; read this column as approximate. Households per band (N): 18–24 N=111, 25–29 N=211, 30–34 N=291, 35–39 N=352, 40–44 N=411, 45–49 N=396, 50–54 N=424, 55–59 N=490, 60–64 N=536, 65–69 N=492, 70–74 N=374, 75 or older N=507. The 18–24 band has the thinnest sample of the twelve; read its 75th and 90th columns as indicative only.
Source: Federal Reserve 2022 Survey of Consumer Finances, public summary extract (fielded 2022; the same file the six-band table above reads), percentiles computed by WealthAge and verified against the Fed’s own published historic table on 9 August 2026. Not the printed bulletin’s own figures, which the Fed computes from a different, internal dataset; see the methodology section for the distinction. These are 2022 dollars; the same CPI-U adjustment used in the age-band table above applies if you want them in June 2026 terms.
The distribution
How unequal is the wealth distribution behind these averages?
The net worth by age table above answers what is typical. This one answers how far apart the top and the bottom of the country actually sit, which is the thing a single median hides.
| Percentile group of net worth | Median, 2022 $ | Mean, 2022 $ |
|---|---|---|
| Less than 25th (bottom quarter) | $3,500 | −$5,300 |
| 25th–49.9th | $93,300 | $98,800 |
| 50th–74.9th | $356,300 | $373,700 |
| 75th–89.9th | $1,036,200 | $1,102,400 |
| 90th–100th (top decile) | $3,794,600 | $7,810,500 |
Source: Board of Governors of the Federal Reserve System, Survey of Consumer Finances, 2022 survey (fielded 2022, published October 2023), Table 2, “Family median and mean net worth, selected characteristics of families, 2019 and 2022 surveys” (the “Percentile of net worth” rows within it), read and verified directly by WealthAge against the Federal Reserve’s published bulletin on 6 August 2026. The bottom quarter’s negative mean reflects households whose debts, largely student loans and unsecured debt, currently exceed their assets.
The June 2026 conversion applies the same 1.1411 CPI-U factor used throughout this page.
Runway
Runway is the number that decides what you can do next
Whether you can take the job, sit out a bad quarter, or say no to work you don’t want is not decided by your net worth. It is decided by runway: how many months the money you can actually reach would cover the bills you have to pay, if the income stopped tomorrow.
It moves for reasons a balance does not. Rent goes up. A car loan ends. A bonus lands. Money sitting in a 401(k) you would pay a penalty to touch is not the same money as cash. Two households with an identical $135,600 net worth, the median for 35 to 44, can be months apart: the one holding index funds can reach its money in a week, the one holding a house and a retirement account cannot.
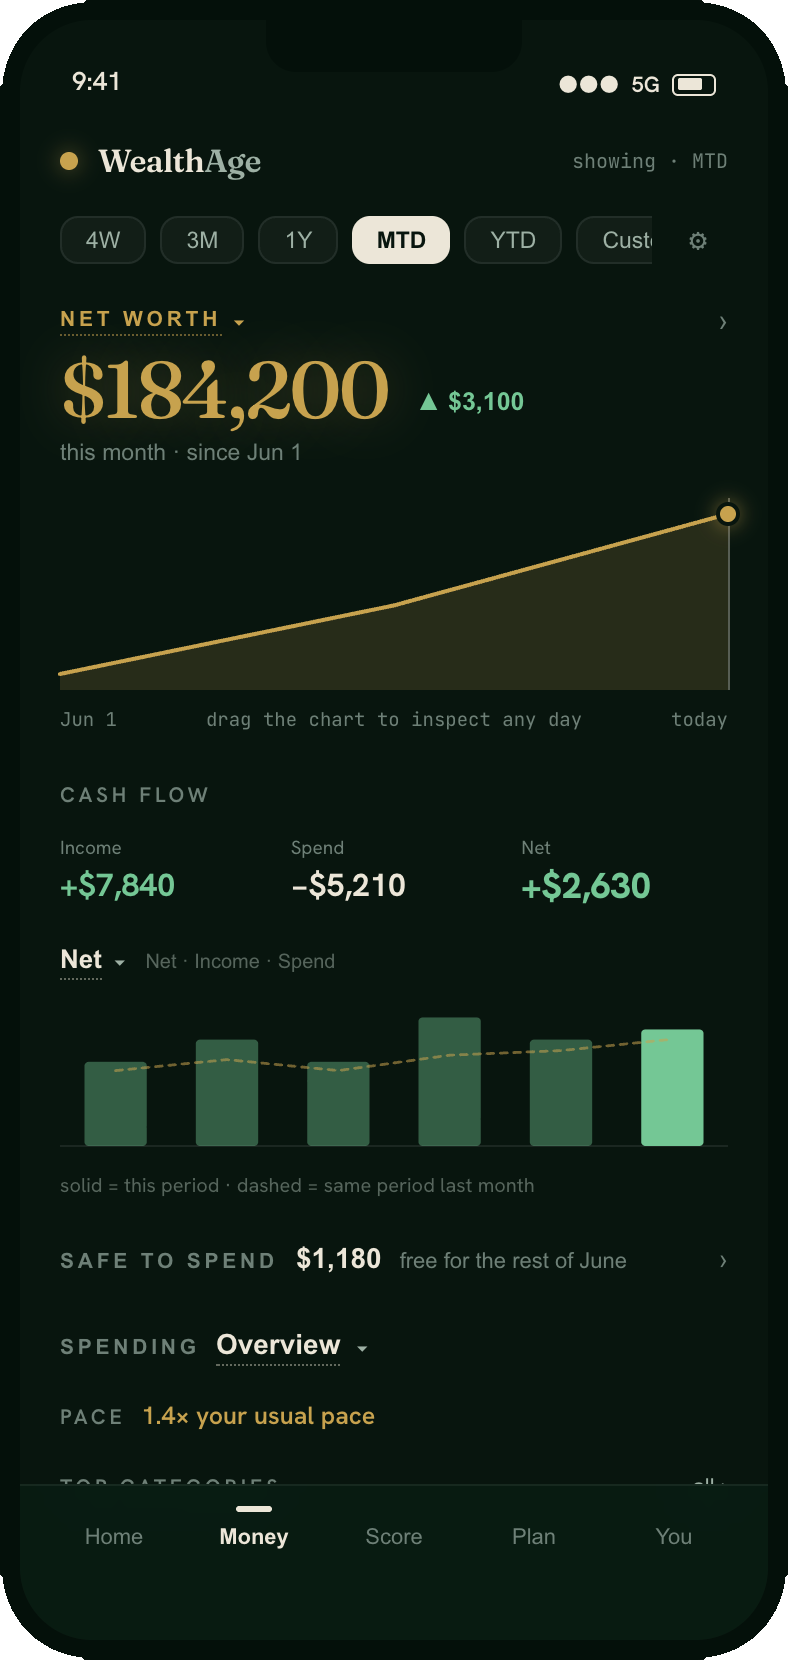
WealthAge brings your accounts, transactions, spending and cash flow into the same place as this arithmetic, connected or uploaded, so you are not redoing it by hand. Your WealthAge score reads how prepared your finances are and names which parts are thin, the reason codes tell you which. You can see an estimate before any of that: the free score estimator asks six questions and gives you a number back, with no bank login and no card.
Connect or upload, and see your runway kept current.
Limits
These figures describe a population in 2022, not your situation today
None of the arithmetic above, the tables or your own runway figure, is complete. Here is what it can’t tell you.
Sampling. The Federal Reserve’s Survey of Consumer Finances samples roughly 4,600 households and weights them to represent about 131 million U.S. households. That’s a sound methodology for the middle of the distribution and a noisier one at the very top, where a handful of extremely wealthy households in the sample can shift the mean substantially. The Fed’s own documentation flags this.
Vintage. These are 2022 figures. Household wealth has moved since the survey was fielded, in both directions depending on the household. The June 2026-dollar columns above adjust for inflation only; they do not and cannot adjust for asset price changes, income growth or debt taken on since 2022.
What’s next. The next wave, SCF 2025, is expected to publish in late 2026. Every number on this page, and every incumbent page in this category, will need updating the day it does. This page is built to re-issue that week.
What the calculator can’t see. It only sees what you enter. It has no visibility into your income, your insurance coverage, your family’s other resources, or how quickly your specific liquid assets could actually be converted to cash in an emergency. Treat its runway figure as a starting estimate, not a guarantee.
Methodology
Every figure on this page traces to a dated source
Those limits are checkable only because every figure here names where it came from. All net worth figures on this page originate from the Federal Reserve Board’s Survey of Consumer Finances, 2022 survey wave, Table 2 of the bulletin “Changes in U.S. Family Finances from 2019 to 2022” (October 2023), read and verified directly against the Federal Reserve’s own published table by WealthAge on 6 August 2026. Inflation adjustments use the Bureau of Labor Statistics’ CPI-U index, comparing the 2022 annual average (292.655) to the June 2026 index (333.952), both not seasonally adjusted: a factor of 1.1411, multiplied by each 2022 figure and rounded to the nearest ten dollars. A 2022 annual average compared against one 2026 month is not the same basis a full 2026 annual average would be, which is why the adjusted columns are headed “June 2026 $” rather than “2026 $.” Every figure here is re-checked against the Federal Reserve’s published tables at each SCF release. The calculator runs on your device; entries are not stored.
The rank feature and the twelve-bracket table above it read from a second, finer analysis of the same Federal Reserve dataset: the 2022 SCF’s public microdata file, downloaded directly from the Federal Reserve and processed by WealthAge, not a secondary reproduction. The Fed multiply-imputes each household five times; WealthAge pools all five using the Fed’s own published weighting convention, the same method the Fed’s own bulletin macros use. The result is computed by WealthAge from the Federal Reserve’s 2022 SCF public microdata and verified against the Fed’s published tables, with every one of the seven age-band medians exact. One distinction worth stating plainly: the printed bulletin table elsewhere on this page comes from the Fed’s internal, non-public dataset, which the Fed itself says cannot be reproduced exactly from the public file; the rank feature and the twelve-bracket table are built entirely on the public file instead, so they are verified against the Fed’s own public-data table, never claimed as a match to the printed bulletin’s internal-data numbers. Full method: the twelve-bracket table above.
Data: Federal Reserve SCF 2022 (published Oct 2023). This page re-issues when SCF 2025 publishes (expected late 2026). Published 6 August 2026. Last reviewed 9 August 2026.
Corrections: 2026-08-06: first publication. 2026-08-09: added net worth percentile ranking by age, twelve WealthAge age bands cut from the Federal Reserve’s public 2022 SCF microdata, verified cell-for-cell against the Fed’s own published table.
Where this page still concedes: dqydj has published net worth percentiles since 2009 and splits its age bands finer, fourteen bands to this page’s twelve, the extra split a larger effective sample buys. What changed here: every median in the rank table is verified exact against the Fed’s own published public-data table, not only derived from the same file, and your rank sits beside a runway number dqydj’s page never computes. WealthAge is web today, built for your phone’s browser.
A percentile is where you stand today. Survival is what happens next.
The tables and the rank above describe a population and a moment, both from 2022 data. What survives a real shock is your own arithmetic, not a percentile.
One limit, plainly: the calculator sees only what you type, and your rank only places your net worth against public data. WealthAge brings the same numbers into the same place as your real accounts, connected or uploaded, instead of a form you fill in once.
WealthAge keeps this arithmetic running on your real accounts, so the number is current the day you need it.
Connect or upload to start.
See how it works